How insurance legal teams can strengthen defensibility across claims, regulatory matters and commercial agreement
Highlights
- Insurance legal teams are judged when scrutiny arrives long after a claim, regulatory or contract decision is made.
- A defensible position shows the facts relied on, governing authority, reasoning and decision-maker across every matter type.
- AI used in this work should be checked for sources, change awareness, jurisdiction coverage and data handling.
The claim was denied eighteen months ago. Today, the file is an exhibit.
Opposing counsel isn’t asking whether the decision was right. They’re asking what the carrier relied on, which law it applied in that state, and who signed off. The adjuster who made the call has moved on, the reservation of rights is in a folder no one can find, and the analysis lives in someone’s inbox.
This is the moment insurance legal teams are really judged. Scruity can come long after the decision is made – when somebody paid to take it apart starts reading the file. That might be a plaintiff’s lawyer building a bad-faith case from your own paper trail, a regulator reviewing claim files, or an arbitrator reading a treaty clause nobody flagged as ambiguous.
The policy is both the product you sell and the rulebook for every claim, and a regulator or court can read how you applied it. Insurance is examined and judged, not just audited. Defending a decision and showing the basis for it are not the same thing, and scrutiny goes straight for the gap between them.
Jump to ↓
Why “every jurisdiction” is where documentation slips
Five questions to ask of any AI used in this work
What legal teams need to show
A defensible position always shows the same four things: the facts relied on, the governing authority, the reasoning that connects them, and who decided. What a reader looks for differs by matter type.
In a claim decision
- Show how the complaint, policy and reservation of rights were read against each other, including which allegations triggered or excluded which provisions.
- Name the jurisdiction and controlling authority in force when the call was made; duty to defend, exclusions and bad-faith standards vary by state.
- Separate the facts available at the time from information received later, then explain the reasoning behind pay, deny or settle.
- Record what was communicated, who approved the decision and when, including any escalation of genuine uncertainty.
In a regulatory matter
- Identify which jurisdictions a rule touches, and why others were ruled out.
- Show what changed across policy forms, claims manuals and letter templates, as well as what was reviewed and left unchanged.
- Trace each jurisdictional position to the statute, regulation or bulletin in force today.
- Document the implementation timeline and explain deliberate variations between states.
In a commercial agreement
- Record the standard used for review, whether a playbook, model document or governing statute.
- Capture every deviation, missing clause and approved exception.
- Where wording is ambiguous, show how it was resolved and what the review covered.
- Maintain version history across drafts and counterparties, including who accepted each change.
The common thread
In all three, the test is the same: could someone who wasn’t in the room reconstruct the position from the file alone? That record needs to remain clear through staff turnover, a gap of eighteen months and scrutiny from a reader paid to find the weak point.
For legal operations, the practical move is to agree what “shown” looks like for each matter type before anyone is under pressure. A short checklist per workflow, applied consistently, does more than reconstruction after the fact.
Why “every jurisdiction” is where documentation slips
Insurance is governed by a patchwork of state, national, and regional requirements. To answer a single question you may need to compare rules across all 50 U.S. states, multiple European jurisdictions, or every market in which the carrier operates. Building that comparison manually means reviewing dozens of sources, identifying meaningful differences, and continually updating the analysis as requirements change.”
When time is short, the paper trail is often the first thing to thin out.
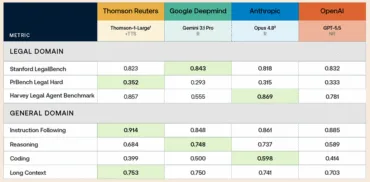
This is also where AI enters the conversation. If technology helps assemble, compare or draft part of the position, legal teams need to be able to scrutinize its contribution as carefully as the underlying work.
The same test applies to AI
The question is what happens when an AI-assisted output is challenged: can anyone show what it was based on?
The profession has named the standard. In the Thomson Reuters Institute’s Future of Professionals Report 2026, professionals said AI tools must safeguard confidential data (96%), ground outputs in authoritative content (94%) and produce reasoning that can be explained and defended (90%). Yet 41% of professionals who use AI at work don’t have access to tools that meet those standards.
Speed is easy to buy. Defensibility isn’t. A faster wrong answer still carries your name, and accountability cannot be delegated to a model.
Five questions to ask of any AI used in this work
- What does it check against? Authority, or only what your team has done before? Precedent is a starting point, but it cannot show whether a position still holds.
- Can you open every source? A citation you can read in the authority’s own words is evidence; a summary you are asked to trust is not.
- Does it know what changed and what is missing? When precedent shifts, does the tool know? Can it flag the clause that should be there and is not?
- Does the answer hold in every jurisdiction you write in? The same verification should apply in each state or market, not only where headquarters sits.
- Where does your data go, and who signs off? Ask whether data trains anything, where it lives, and how outputs fit your review and approval process.
These are the questions a regulator or court would put to the work itself, so put them to the tool before it becomes part of the file.
Go deeper
Insurance legal work is often examined long after a decision is made. Discover how trusted legal content and AI can help insurance legal teams when their decisions come under scrutiny.